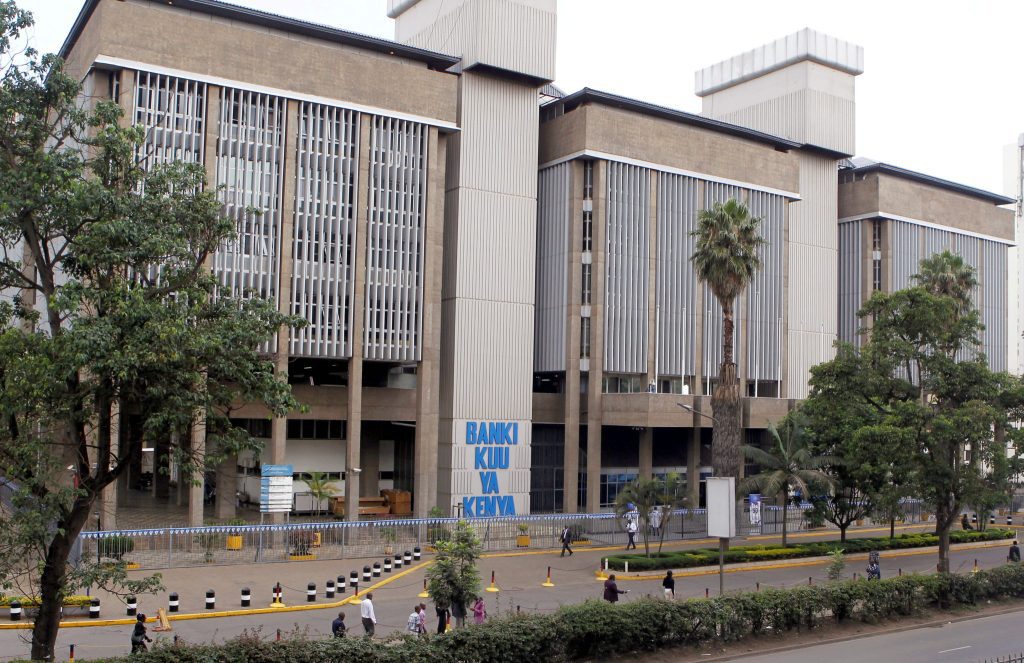
Kenya is set to issue payment licenses to fintech companies, signaling a shift in regulatory policy that could open East Africa’s largest payments market to startups like Flutterwave and Chipper Cash. The Central Bank of Kenya (CBK) is revising the National Payment Systems Act of 2011 to create a legal framework for fintech operations, a move that could end longstanding legal ambiguities.
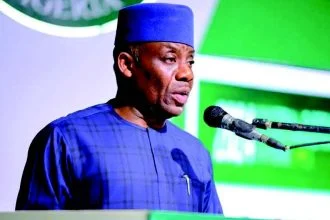
CBK governor Kamau Thugge stated that the updated legislation would provide clear guidelines for registering and licensing fintechs. This development is particularly significant for remittance and payment providers that have faced scrutiny and asset freezes from Kenyan authorities over allegations of money laundering.
Currently, Kenya’s financial sector is governed by the Central Bank of Kenya Act, the National Payment Systems Act, and associated regulations. However, these frameworks primarily focus on traditional financial institutions, leaving fintechs in a regulatory grey area. This has historically allowed banks and telecom companies to dominate the payments landscape while restricting the growth of newer entrants.
Thugge acknowledged the need for reform during a post-monetary policy briefing, emphasizing the importance of updating the Payments Act and related regulations to ensure fintech startups can operate within the law. These changes aim to bring clarity and stability to the payments sector, enabling greater competition and innovation.
In 2022, the CBK instructed local banks and mobile money operators to sever ties with fintechs, citing risks to financial stability. This decision, coupled with investigations and asset freezes by agencies like the Financial Reporting Centre (FRC) and the Asset Recovery Authority (ARA), underscored the regulatory challenges fintechs faced in Kenya.
The proposed amendments to the National Payment Systems Act could mark a turning point for the sector, offering a pathway for startups like Flutterwave and Chipper Cash to establish a legal foothold in one of Africa’s most dynamic markets. These changes could also foster a more inclusive financial ecosystem by allowing fintechs to compete on equal terms with established players.